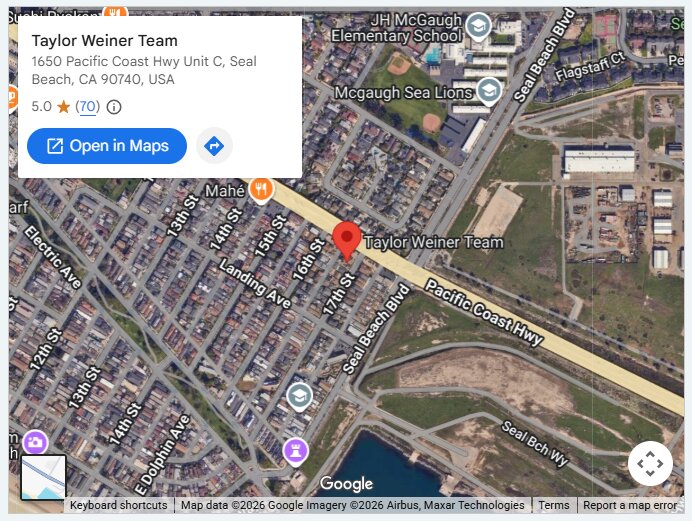
The Taylor Weiner Team is a mortgage team based at 1650 Pacific Coast Highway in Seal Beach, California, serving Orange County, Los Angeles and borrowers throughout California. The team originates residential mortgage loans as part of Lower, LLC (NMLS ID# 1124061). This release summarizes the team's tabulation of 2025 Home Mortgage Disclosure Act (HMDA) data for Orange County, published by the Federal Financial Institutions Examination Council (FFIEC). The tabulation covers 14,454 decided home-purchase applications, sets out the reasons lenders reported for the 1,448 that were denied, and explains what those reasons mean for buyers preparing to apply.
The debt-to-income ratio was the reason lenders cited most often when they denied Orange County home-purchase mortgage applications in 2025, according to a Taylor Weiner Team tabulation of federal HMDA data. Lenders listed debt-to-income on 597 of the 1,443 denials that gave a reason (41.4%). Collateral, which covers the appraisal and the property, was cited on 25.6%, and insufficient cash for the down payment or closing costs on 13.5%. Lenders denied 1,448 of 14,454 decided applications for owner-occupied, first-lien home purchases in the county, a denial rate of 10.0%, up from 9.0% (1,365 of 15,083) in 2024. The source is the FFIEC's HMDA Data Browser for Orange County, California (county 06059), queried September 23, 2026.
Why were Orange County home-purchase mortgage applications denied in 2025?
Lenders can report up to four denial reasons on each application. The shares below use the 1,443 Orange County denials in 2025 that listed at least one reason, so they add up to more than 100%.
- Debt-to-income ratio: cited on 597 denials (41.4%), up from 40.2% in 2024.
- Collateral: cited on 370 denials (25.6%), up from 22.8% in 2024.
- Insufficient cash (down payment, closing costs): cited on 195 denials (13.5%), up from 11.5% in 2024.
- Credit application incomplete: 11.5%. Unverifiable information: 10.7%. Credit history: 6.6%. Employment history: 2.9%.
Debt-to-income denials were rarely close calls. On 490 of the 597 denials that cited debt-to-income (82.1%), the lender reported a ratio above 50%. HMDA reports the ratio the lender relied on, in bands.
How did denial rates differ by loan type and loan size?
The same 2025 Orange County dataset shows different denial rates by program and by loan size:
- Conventional: 1,305 of 13,223 decided applications denied (9.9%).
- FHA: 103 of 771 denied (13.4%).
- VA: 40 of 460 denied (8.7%).
- Within the conforming loan limit: 9.5% denied (1,093 of 11,547).
- Above the conforming limit (jumbo): 12.2% denied (355 of 2,907). Debt-to-income was the most-cited reason in this group as well.
For comparison, across all home-purchase applications of every lien and occupancy type, the FFIEC Data Browser's 2025 aggregates show a denial rate of 11.7% in Orange County, 11.2% in California and 13.9% nationally.
How does the Taylor Weiner Team use this data with buyers?
Three things drove most of the reported 2025 denials: the ratio of debt to income, the property and its appraisal, and the cash needed to close. Each one can be checked before a buyer writes an offer. The team's affordability calculator works out a buyer's maximum from four separate ceilings: the debt-to-income ratio, available cash, the county loan limit and, on VA loans, the residual income test. It then names the one that limits the buyer. The team's home-buying process starts with a verified pre-approval so that income, credit and assets are reviewed before the buyer starts shopping.
"Most of these denials came down to a number that could have been measured before the buyer made an offer, whether that was the ratio, the cash to close or the appraisal," said Taylor Weiner, Senior Mortgage Advisor, the Taylor Weiner Team (NMLS 263090). "The time to learn which of those limits applies to you is before you are in escrow, when there is still room to pay down a balance, add documented gift funds or look at a different price range."
Buyers can compare the loan programs the team offers and contact the Taylor Weiner Team to go through their own numbers before they apply.
Methodology
The data are public, loan-level HMDA records for 2025 downloaded from the FFIEC HMDA Data Browser (ffiec.cfpb.gov) on September 23, 2026, filtered to Orange County, California (county 06059) and home purchase. The core population covers first-lien loans for a principal residence on site-built one-to-four-unit properties. It excludes reverse mortgages, open-end lines of credit and business-purpose loans. "Decided applications" means loans originated, applications approved but not accepted, and applications denied. Withdrawn applications, files closed for incompleteness, preapproval-only requests and purchased loans are excluded. For that population, 413 reporting institutions filed 2025 records in the county. The same filters were applied to 2024 data.
Denial reasons are the lender's own reported reasons, using the HMDA codes published in the FFIEC's public data-field documentation. Not every lender is required to report under HMDA, so the data do not cover every mortgage application in the county. The counts describe applications, not individual people. The figures describe what lenders reported. They do not measure causes, and they do not predict the outcome of any individual application. The Consumer Financial Protection Bureau announced the release of the 2025 HMDA data on March 31, 2026.
Key Features and Facts
- Location: 1650 Pacific Coast Highway Unit C, Seal Beach, CA 90740, serving Orange County, Los Angeles and borrowers throughout California.
- Core services: Purchase and refinance lending across fixed-rate, adjustable-rate, FHA, VA, USDA, jumbo and interest-only loans, reverse mortgages, CalHFA MyHome and GSFA Platinum down payment assistance, and non-QM programs (bank statement, DSCR, 1099, P&L, asset-based), plus HELOC and home equity loans.
- Licensing: Taylor Weiner, Senior Mortgage Advisor, NMLS 263090, California. The team originates as part of Lower, LLC, NMLS ID# 1124061.
- 2025 Orange County home-purchase denial rate (HMDA, owner-occupied first lien): 10.0% (1,448 of 14,454), up from 9.0% in 2024.
- Most-cited 2025 denial reason in Orange County: debt-to-income ratio, on 41.4% of denials that gave a reason. On 82.1% of those, the lender reported a ratio above 50%.
About the Taylor Weiner Team
The Taylor Weiner Team is a mortgage team based in Seal Beach, California, that helps buyers and homeowners in Orange County, Los Angeles and throughout California purchase, refinance and access home equity. The team originates residential mortgage loans as part of Lower, LLC (NMLS ID# 1124061), 5950 Symphony Woods Road, Suite 312, Columbia, MD 21044. Taylor Weiner NMLS 263090. Equal Housing Opportunity. Licensing can be verified at nmlsconsumeraccess.org. Not an offer of credit or commitment to make a loan. All approvals are subject to underwriting guidelines. Loan programs and options are subject to change at any time. The Taylor Weiner Team is not affiliated with or endorsed by the FFIEC, the CFPB or any government agency. Visit twteam.com for more information.
Media contact
Taylor Weiner
Senior Mortgage Advisor, NMLS 263090
The Taylor Weiner Team
Phone: (714) 658-4912
Email: tweiner@twteam.com
1650 Pacific Coast Highway Unit C
Seal Beach, CA 90740
https://www.facebook.com/loansbytaylorweiner/
https://www.linkedin.com/in/taylor-weiner-22607053/
https://www.yelp.com/biz/taylor-weiner-team-seal-beach
https://www.zillow.com/lender-profile/tweiner3/
newsroom: news.38digitalmarket.com
Source: 38 Digital Market News
Release ID: 2660853